The Great Enterprise AI Gap: Why Near-Universal Adoption Hasn't Translated to Transformation in 2026
Enterprise AI adoption is near-universal, but measurable transformation remains elusive. A deep dive into the governance, workforce, and strategy gaps separating AI winners from everyone else.
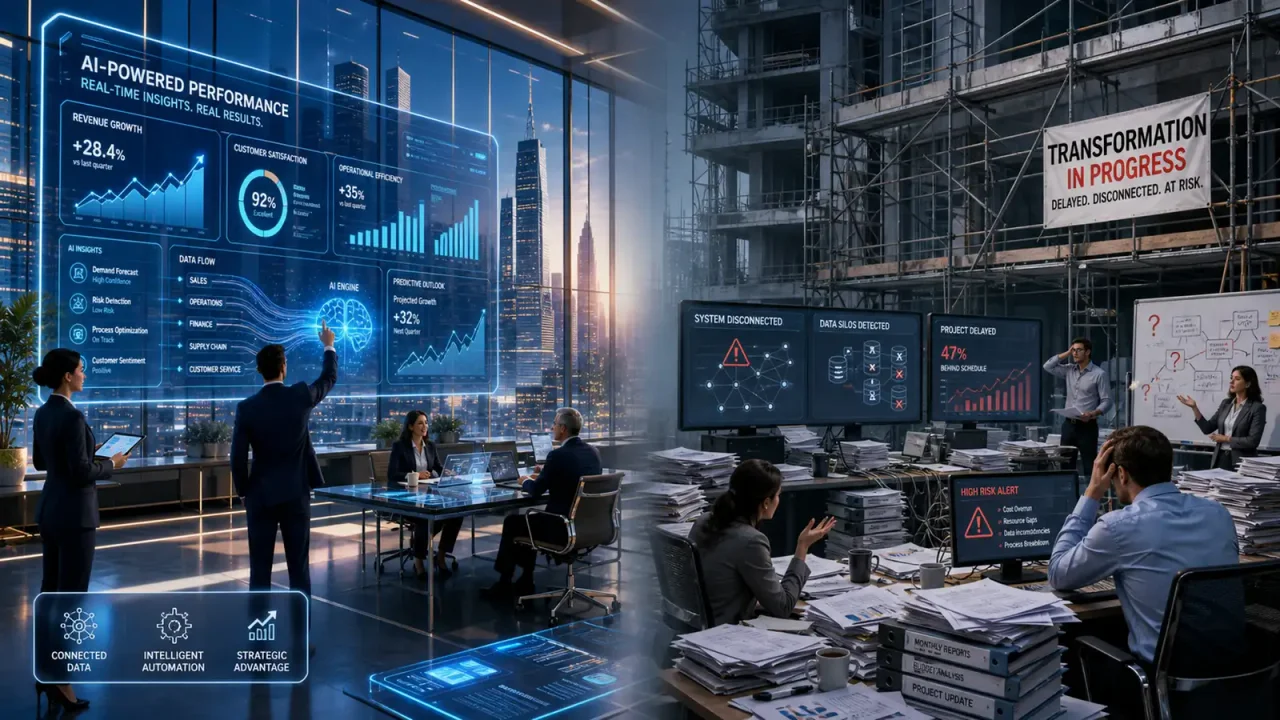
By almost every available metric, enterprise artificial intelligence has crossed a threshold in 2026 that would have seemed implausible just eighteen months ago. In McKinsey’s 2025 State of AI survey, 88 percent of respondents said their organizations regularly use AI in at least one business function. Gartner forecasts that worldwide AI spending will total about $2.5 trillion in 2026, a 44 percent jump that rewrites every investment forecast boardrooms drafted two years ago. Gartner also predicts that by year’s end, 40 percent of enterprise applications will embed task-specific AI agents, up from less than 5 percent in 2025.
By the numbers, it is a revolution. By the balance sheet, it is something considerably more complicated.
Deloitte’s 2026 State of AI in the Enterprise report captures the paradox with unusual candor. Most organizations report productivity and efficiency gains from their AI investments. Far fewer can articulate AI’s contribution in boardroom language, and fewer still have translated it into regular board-level reporting. The gap between adoption and transformation is widening, and it is doing so at the exact moment enterprises are betting their largest technology budgets in history on closing it.
The Numbers Tell One Story. The Org Chart Tells Another.
The raw statistics of enterprise AI in mid-2026 are staggering. McKinsey estimates that generative AI alone could add between $2.6 trillion and $4.4 trillion annually to the global economy. Yet most organizations are still early in turning agent experiments into production deployments.
Yet beneath the spending surge lies a structural problem that no amount of compute can solve. According to Deloitte’s board governance survey, 66 percent of respondents say their boards still have limited-to-no knowledge or experience with AI — an improvement from 79 percent in the previous survey, but still a majority. These are the same boards approving eight-figure AI budgets. The same boards holding quarterly reviews where AI ROI is expected to be demonstrated. And increasingly, the same boards asking pointed questions that their organizations struggle to answer.
“Adoption is no longer the hard part,” the Deloitte report notes, in what may be the most consequential sentence in enterprise technology this year. “While enterprise AI adoption has become widespread, many companies are still behind on the changes that may matter most: redesigning how work gets done, defining how autonomy should be governed, and building ways to measure what actually matters.”
This framing represents a decisive shift in how the industry thinks about AI transformation. For three years, the dominant narrative positioned adoption as the primary obstacle — get the tools into the workforce, train people on prompts, and value would follow. The data from mid-2026 tells a different story. Adoption happened faster than anyone predicted. Value capture did not.
The Agentic Inflection Point
The clearest illustration of the adoption-transformation gap sits at the most hyped frontier of enterprise AI: agentic systems. Gartner’s 2026 Hype Cycle places agentic AI squarely at the “Peak of Inflated Expectations,” a designation that simultaneously acknowledges the technology’s extraordinary promise and warns of the disillusionment that historically follows.
The momentum behind the hype is real. Gartner forecasts that task-specific AI agents will feature in 40 percent of enterprise applications by the end of 2026. In manufacturing and logistics, the combination of digital agents and edge hardware is being described as the highest-impact opportunity in a generation.
But dig one layer deeper and the picture fragments. The gap between organizations “using” agents and those deploying them at meaningful scale is where the real story lives. Most enterprises are running agentic pilots in sandboxed environments — impressive demos that handle customer service triage or internal document retrieval but stop short of touching production systems, regulated data, or revenue-critical workflows. The architecture exists. The governance does not.
Gartner’s workforce projections capture the tension. Rather than a “jobs apocalypse,” the firm describes a coming period of “job chaos,” with more than 32 million jobs a year expected to be reconfigured or redesigned by the end of the decade. The language is deliberate. Transformation is not elimination — but it is not stability either. Enterprises that fail to build the retraining pipelines, role redesign frameworks, and human-AI collaboration protocols to absorb that transformation will find themselves with expensive agentic capabilities and a workforce structurally incapable of using them.
Governance: The Unsexy Bottleneck
If there is a single thread connecting the enterprises that have successfully crossed from adoption to transformation, it is governance. And governance, in mid-2026, remains the enterprise AI conversation that almost nobody wants to have.
The regulatory backdrop tells its own story: voluntary frameworks like the NIST AI Risk Management Framework sit alongside a rapidly expanding patchwork of state-level rules. The governance tooling landscape has splintered into dozens of platforms, each promising to solve a different slice of the problem — bias detection, model explainability, compliance documentation, access control, audit trails.
But governance is not a software problem. It is a leadership problem. The organizations reporting the strongest AI returns, according to multiple 2026 surveys, are the ones that built governance disciplines before they built models. They established clear lines of accountability for AI-driven decisions. They defined what “autonomy” means in operational terms, not marketing ones. They created feedback loops between the teams deploying AI and the teams measuring its impact. And they did something that sounds mundane but turns out to be revolutionary: they required management to report AI investment performance using consistent, auditable metrics — total capital deployed, measured financial returns by initiative, and portfolio-level ROI — on a quarterly basis.
The gap between these organizations and everyone else is not a gap of technical sophistication. It is a gap of organizational discipline.
The Boardroom Is the New Bottleneck
The Deloitte finding that two-thirds of boards lack AI experience should be read alongside the persistent ROI gap. The causality runs in both directions. Confidence follows results, but results follow the kind of strategic clarity that only an informed board can provide.
In 2026, board directors have moved past the initial awe of generative models. They are asking the hard questions: What is the total AI capital deployed year to date? Which initiatives are generating measured financial returns, and which are consuming budget without measurable output? How does the AI portfolio’s blended ROI compare with other capital allocation options? These questions are reasonable. They are also, for most enterprises, unanswerable at present.
The organizations that can answer them share a common architecture. They treat AI not as a collection of point solutions but as a capability embedded within the broader technology stack — no different, in strategic terms, from cloud infrastructure or data platforms. They have moved beyond “pilot purgatory,” the defining trap of 2026, where experiments multiply but never reach production.
What the Winners Are Doing Differently
Across the research, a consistent profile of the AI transformation leader emerges. These organizations share several characteristics that have little to do with model selection or vendor relationships.
First, they have reorganized around outcomes rather than tools. Instead of standing up an “AI center of excellence” that operates as a separate entity, they have embedded AI capability inside existing functions — finance, supply chain, customer experience, product development — with clear ownership and clear metrics. The technology follows the org chart, not the other way around.
Second, they have invested disproportionately in the “last mile” of AI deployment: the workflow redesign, the retraining, the change management that determines whether a technically sound model generates actual business value. The most sophisticated large language model in the world produces zero ROI if nobody changes how they work to use its output.
Third, they have built measurement systems before they built models. They defined what success looks like in operational terms — reduced cycle time, increased conversion rate, lower error frequency — and instrumented their processes to track those metrics before deploying AI into them. This sounds obvious. It is vanishingly rare.
Fourth, and perhaps most importantly, they have confronted the governance question directly. They have not waited for regulation to force their hand. They have established AI governance frameworks that specify who is accountable when an AI agent makes a decision, how those decisions are audited, and what happens when they go wrong. In an era where agentic AI is moving from demos to production, this is not a compliance exercise. It is a precondition for scaling.
The Road Ahead
The enterprise AI story of 2026 is not a story of technology limitations. The models are powerful enough. The infrastructure exists. The talent, while scarce, is available. The bottleneck is something older and more familiar: the ability of large organizations to change how they operate.
Gartner’s 32 million transformed roles will not transform themselves. The organizations planning agentic deployments in the next two years will not succeed by buying more software. The board members currently approving AI budgets without understanding what they are buying will not suddenly develop literacy through quarterly PowerPoint decks.
The enterprises that cross the adoption-transformation gap will be the ones that treat AI not as a technology initiative but as an operating model transformation. They will build the governance, the measurement, and the workforce architecture first — and the models second. For everyone else, 2026 will look a lot like 2025 looked: more pilots, more spend, more hype, and an ROI conversation that never quite lands.
The gap is real. The path across it is clear. What remains to be seen is how many organizations have the courage to take it.
Sources and further reading
- McKinsey, The State of AI
- Stanford HAI, AI Index Report
- NIST AI Risk Management Framework
- Brynjolfsson, Rock & Syverson, The Productivity J-Curve (NBER w25148)
Our analysis: High adoption with low transformation is consistent with the productivity J-curve described by economists: organizations must reorganize work before gains appear in the numbers.